

Service Areas
About Gus Marin
Gus Marin is a trusted Space Coast Realtor serving Melbourne, Viera, Palm Bay, Cocoa, Melbourne Beach, and all of Brevard County, with more than 12 years of experience helping buyers, sellers, first-time home buyers, military families, luxury clients, and aerospace relocation professionals make confident real estate decisions.
Originally from Colombia and fluent in both English and Spanish, Gus is known for blending high-end digital marketing, cinematic property storytelling, strong negotiation, and concierge-level service with something even more important: honesty and human connection.
His philosophy is simple. While many agents focus on the paycheck, Gus focuses on the family behind the move.
He believes the right home is not just the one that looks good online. It must be the right fit, the right price, the right lifestyle, and clear of issues that could create regret later. From helping buyers identify defects, insurance risks, resale potential, and neighborhood fit, to helping sellers position their homes with premium marketing exposure across 725+ online platforms, Gus puts peace of mind and long-term value first.
What truly sets him apart is his willingness to tell clients the truth, even when that truth may slow down or even cost a deal. For Gus, the real reward is not simply reaching the closing table. It is knowing he helped a family step into the right home, create lasting memories, and feel confident they made the best decision for their future.
That people-first approach has built a business fueled by repeat clients, military referrals, first-time buyers, luxury sellers, relocation families, and long-term relationships rooted in trust.
If you are planning a move anywhere on the Space Coast and want a local expert who combines AI-powered marketing, local lifestyle expertise, and honest guidance, Gus Marin is ready to help you move with confidence.
OTHER LANGUAGES
Credentials
LICENSE
Designation
Military Relocation Professional
Specialties
- Buyer's Agent
- Divorce Sales
- Investment Properties
- Landlord
- Listing Agent
- Military/Veterans
- Probate & Trust Sales
- Property Management
- Real Estate Consulting
- Relocation
- Single-Family Homes
Awards
-


2024
TOP AGENT
Palm Bay, FL
2024
TOP AGENT
Melbourne, FL
2024
TOP AGENT
Cocoa, FL
Answered Questions
Putting your daughter on the title of your home may sound simple, but it's one of those decisions that can have major legal and tax consequences if it's not handled the right way. Yes, it can sometimes help avoid probate, but it also means she becomes a legal co-owner right away. That means any future issues on her side, like creditors, lawsuits, or even divorce, could potentially affect the property. Another important thing to consider here in Florida is how it may impact your homestead protections and future tax benefits. If the home has gained a lot of value over the years, it could also create capital gains issues later when the property is sold. My honest advice is to always speak with a Florida real estate attorney or estate planning professional before making that move. Sometimes there are better ways to protect the property, keep control, and still make the transfer easier for your family in the future.
A restrictive covenant is very different from a zoning issue, so the first thing to know is that a variance usually will not solve the covenant itself. A variance is something you request from the city or county for zoning rules, while a restrictive covenant is a private deed restriction tied to the property. The good news is that because this covenant dates back to 1954, the first step is to find out whether it is even still enforceable. Many older restrictions either expire, were never renewed properly, or no longer reflect the way the neighborhood has developed over time.
My real-world rule: If I see an older condo with low reserves + recent repair discussions + rising insurance, I assume there is a very real chance of a large assessment. The safest move is to ask directly in writing: " Are there any pending, discussed, or anticipated special assessments or major repairs being considered by the board?aEUR? That written answer matters. If anything feels borderline, negotiate one of these before closing: seller credit price reduction escrow holdback seller pays any assessment approved within a certain period In today's Florida condo market, especially with reserve law changes, this due diligence is no longer optional. It's one of the most important parts of protecting your budget before you buy.
The idea is this: Instead of making one full mortgage payment each month, you make half the payment every two weeks. Because there are 52 weeks in a year, paying every two weeks means you end up making the equivalent of 26 half payments, which equals 13 full monthly payments per year instead of 12. That one extra payment each year goes directly toward reducing your principal balance faster. Why that matters: lower principal balance = less interest charged over time your loan amortizes faster you can shave several years off a 30-year mortgage you can save a significant amount in total interest The reason it feels easy is because you're not really " doublingaEUR? anything. You're just aligning payments with a biweekly schedule, which often matches how many people get paid. One thing to be careful with: some lenders offer a " biweekly payment program,aEUR? but they may charge fees for it. In many cases, you can accomplish almost the same result by simply making one extra mortgage payment per year or adding 1/12 of a payment extra each month toward principal. For example, if your mortgage payment is $2,400: normal = $2,400 x 12 = $28,800 per year biweekly = $1,200 every 2 weeks = $31,200 per year That extra $2,400 each year is what accelerates the payoff. So yes, it works because you're making the equivalent of one extra payment every year, and over time that can dramatically reduce both years and interest.
This is a great question, and honestly most people feel the exact same way the first time they see a title report. You do not need to understand every legal word in all 40 pages. The key is knowing which sections can actually affect your ownership, use of the property, or future resale. Here's what I would focus on first: Who currently owns the property Make sure the seller's name matches exactly and that there are no unexpected additional owners. Legal description Confirm the lot, block, unit, and parcel description matches the property you believe you are buying. Liens and judgments The lien from 1994 needs attention. The main question is whether it is still active or already satisfied. A lot of older liens remain in the record even after being paid, so the title company should confirm whether it will be cleared before closing. Easements Easements are very important because they can affect how you use the property. Common ones include utility lines, drainage, access roads, shared driveways, or neighboring access rights. The real issue is whether the easement runs through an area where you may want to build a pool, fence, ADU, garage, or addition. Restrictions / covenants Watch for HOA rules, setback restrictions, no secondary dwellings, rental limitations, or use restrictions. Boundary / survey exceptions This section can reveal encroachments, fence issues, shared walls, or property line conflicts. The easiest way to simplify the whole report is to ask your title company or closing attorney this exact question: " Can you highlight anything in this report that affects my ability to use, improve, insure, or resell the property?aEUR? That one question cuts through all the legal language and gets you to what really matters. My real-world advice: the two items you already noticed, the easement and the old lien, are exactly the right things to focus on first. The easement affects future plans, and the lien affects whether you receive clean title at closing. Everything else is mostly supporting paperwork unless it limits what you can do with the property.
From my experience, it usually makes more sense to buy when the home, the payment, and your lifestyle timing all make sense, instead of trying to perfectly time interest rates. Yes, rates are higher than the 3% era, but the reality is most forecasts only show a gradual decline, not a dramatic drop. Even if rates ease later, it may only be a small difference in monthly payment. What buyers sometimes miss is this: If rates drop, more buyers jump back in competition increases homes start getting multiple offers again sellers regain leverage prices often move up So while the rate may improve a little, the price you pay for the home could easily increase, and that can cancel out the savings. Right now, buyers often have stronger negotiating power: price reductions seller credits closing cost help rate buydowns less competition more time to make decisions That leverage can be worth more than waiting for a slightly lower rate. My honest advice is simple: buy now if the payment feels comfortable today and the home fits your 3"5 year plan. If rates come down later, you can always refinance. But if the payment today feels too tight, then waiting may be the smarter move because your peace of mind matters more than forcing a deal. I always tell buyers: marry the house, date the rate. The home is the long-term asset. The rate is the part you can change later.
If you want to live by the ocean in Florida, plan for 3 types of insurance, not just one. Homeowners insurance: covers the house, belongings, liability, fire, theft, plumbing leaks, and usually wind with a hurricane deductible Flood insurance: separate policy, often required near the ocean or in flood zones Wind/hurricane protection: usually part of the main policy, but roof age, shutters, impact windows, and distance to the water heavily affect cost A safe coastal budget is usually: $5,000"$8,000/year for a newer, well-protected home $8,000"$12,000+/year for older beachside or flood-zone homes The biggest price factors are the roof, flood zone, age of the home, and how close you are to the water. My best advice: always get an insurance quote before the inspection period ends, because in Florida that number can make or break the monthly payment.
Moving from Florida to Illinois is pretty simple, and there's no tax or special fee just for leaving Florida. The main things you need to do are: update your driver's license and car registration change your address with banks, work, insurance, and voter registration set up mail forwarding update your payroll tax withholding, since Illinois has state income tax and Florida does not If you move mid-year, you'll usually file an Illinois part-year state tax return, but there's no Florida state return. Since you're looking outside Chicago, my biggest advice is to watch the property taxes, because they can be much higher than buyers expect and can really change the monthly payment.
# Selling Your Home As-Is After 38 Years | Your Complete Guide First, congratulations on 38 years of homeownership. That is a real accomplishment, and being ready for the next chapter is something to celebrate, not stress over. Here is the full picture, start to finish. --- **Step 1: Have a Real Conversation First** Before anything else, sit down with a local Realtor to talk through your goals, your timeline, and the honest condition of the home. No pressure, no obligation. Just clarity. This conversation shapes everything that follows. **Step 2: Get Your Real Number** A Comparative Market Analysis (CMA) shows you what homes in your area have actually sold for, including as-is sales. This is not a guess or a Zillow estimate. It is your real starting point, and it is free. After 38 years, you have almost certainly built significant equity. As-is does not mean giving the house away. **Step 3: Choose Your Buyer Strategy** As-is has two lanes and both are valid: - **Cash buyers and investors** | Faster close (10 to 21 days typically), lower offers, zero repairs, zero inspection contingencies holding the deal hostage - **Traditional market listing** | Wider buyer pool, higher potential price, some buyers may still request credits but you are never obligated to say yes Your timeline and your bottom number decide which lane fits. **Step 4: Light Prep That Costs Almost Nothing** As-is does not mean as-abandoned. Declutter, clean, and let the space breathe. Remove excess personal items and give buyers room to imagine themselves there. Buyers forgive wear. They do not forgive neglect. Simple prep makes a real difference in both price and speed. **Step 5: Disclose What You Know** Florida law requires sellers to disclose known material defects. This protects you legally, filters out buyers who will waste your time, and keeps the deal from falling apart at the finish line. **Step 6: Price It to Attract, Not to Apologize** As-is homes priced right sell fast. Priced too high, they sit and get stigmatized. The CMA tells us exactly where to land so you attract serious buyers from day one. **Step 7: Controlled Showings Only** You set the schedule. No surprise calls, no revolving door. A good agent uses a showing system that screens buyers before they ever contact you. You stay in control of your home and your peace of mind throughout the process. **Step 8: Review Offers Together** We look at the full picture, not just the price. Cash offers, closing timelines, contingencies, and terms all matter. The right offer is the one that fits your goals, whether that is the highest number, the fastest close, or the least amount of hassle. **Step 9: Close and Move Forward** The title company handles the paperwork. You show up, sign, and walk into your next chapter. --- The very first move is simple. One conversation, one honest look at your numbers, zero pressure. Everything else flows from there. Ready to take that first step? *"Most people don't need more information. They need more clarity."*
Contact Information
Location
Social Media


Available Listings View All
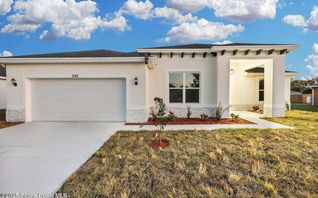
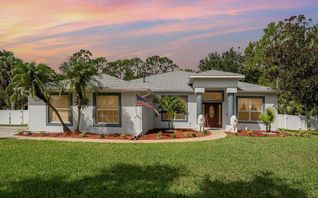
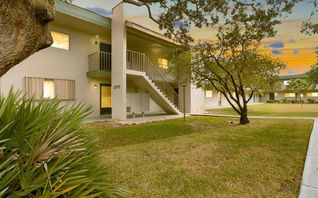
 View All Listings
 ZillowVERIFIED