

Service Areas
About Mike Fielder
Mike Fielder is the Sales Director and Team Lead of The Key Home Team, a top-producing real estate group associated with Cummings & Co. Realtors in Lutherville-Timonium, Maryland. With over 11 years of local industry experience, Mike Fielder represents buyers, sellers, and investors throughout Baltimore City and Baltimore County. He leads a dedicated team of agents who specialize in residential sales, first-time homebuyer education, and property management. The Key Home Team leverages the resources of Cummings & Co. Realtors to provide comprehensive market analysis and transaction support.
Mike Fielder serves a broad territory, with a specific focus on Towson, Lutherville-Timonium, Owings Mills, and North Baltimore neighborhoods like Wyman Park and Hamilton. Beyond traditional sales, Mike Fielder manages investment portfolios through his affiliation with Property Management of Baltimore, LLC. This dual expertise allows him to advise clients on both the livability of a home and its long-term rental viability. A graduate of Towson University, Mike Fielder possesses deep roots in the community and extensive knowledge of regional market trends.
The results demonstrate his leadership; The Key Home Team generates over $30 million in annual sales volume, consistently ranking among the area's high performers. Based at the Cummings & Co. office at 108 W Timonium Rd, Mike Fielder guides clients through complex negotiations in Harford County, Parkville, and Pikesville. Whether securing a primary residence or expanding an investment portfolio, Mike Fielder delivers proven results backed by over a decade of operational excellence.
OTHER LANGUAGES
Community Involvement
HOBBIES/INTEREST
FAMILY
Credentials
LICENSE
Specialties
- Buyer's Agent
- Listing Agent
- Property Management
- Relocation
Awards

FAQ
Answered Questions
Great question, and honestly one that comes up more than you'd think. The short answer is: it depends entirely on what your listing agreement actually says. Every agent relationship is governed by a written listing agreement, and that contract spells out exactly when a commission is earned. Most standard listing agreements (including the Maryland Association of Realtors form) include three triggers: the broker produces a ready, willing, and able buyer at your price; you enter into a contract to sell during the listing term; or you sell the home within a certain window after the agreement ends to someone who toured it or was introduced to it during the listing period. That last one is called a "protection period" or "safety clause," and the length of it is typically filled in as a blank in the contract, often 30 to 90 days. So if you terminated the agreement and are now wondering about a fee, the first thing to do is pull out that listing agreement and check two things: how many days the protection period is, and whether the person you're selling to (or considering selling to) had any contact with the property during the listing term. If the fee feels unreasonable or the situation doesn't clearly fall under the contract language, go directly to the broker. The listing agreement is between you and the brokerage, not just the individual agent, so the broker has authority to negotiate or waive fees. And if there's a meaningful dollar amount at stake, a quick consult with a Maryland real estate attorney is well worth it. Many will do a short consult for free or a flat fee, and they can tell you exactly where you stand. Bottom line: you likely have more options than you think, but the contract language is everything.
Great question, Harriet, and it comes up a lot in the Baltimore area especially since the market there has such a mix of townhomes, rowhomes, and condos. The short answer is: closing costs are mostly price-driven, not property-type driven. Transfer and recordation taxes in Maryland are based on the sales price, and the same goes for lender fees, title insurance, and prepaid items like homeowners insurance and property tax escrow. So a $350,000 townhouse and a $350,000 single-family home will have very similar closing cost numbers. Where you do start to see differences is with condos. Condos often come with a few extra costs that townhouses and houses don't. You'll typically see a condo questionnaire fee (the lender orders a document from the condo association to verify things like HOA financials and reserve funds), and sometimes a move-in fee charged by the association itself. If the condo has special assessments or a low reserve fund, that can also affect your loan options. In Maryland, a good rule of thumb for buyers is to budget 2 to 3 percent of the purchase price for closing costs, though it can vary depending on your loan type (FHA, VA, conventional) and whether you negotiate seller help with closing costs. The best way to get an accurate number early is to ask your lender for a Loan Estimate. That document breaks down every line item so there are no surprises at the closing table.
Eddie, this comes up more than you'd think, especially with sellers relocating internationally. Here's how I'd approach it. The cleanest route is a separate bill of sale. Lenders won't allow personal property like furniture to be rolled into the home's purchase price because it can affect the appraisal, so keeping it separate protects you legally and keeps the transaction clean. The buyer pays for the furniture outside of closing, it gets documented in a simple bill of sale, and everyone moves on without complications. That said, how you market it matters. If the furniture is quality and the house shows well furnished, lean into it. Present the listing as turnkey or move-in ready and let buyers know the furniture is available for purchase separately. In my experience, buyers who are relocating to the area, or investors picking up a rental property, are often the most interested in a furnished home since it saves them time and gives them a head start. There's also a third option worth knowing about in Maryland. The Maryland as-is addendum includes a clause that both buyer and seller initial to waive the standard contract requirement to deliver the property free and clear of trash, debris, and contents. Essentially, both parties agree that whatever is in the property at closing stays. It's most commonly used with distressed properties, but it can work here too. The catch is that the buyer is inheriting the removal burden, so the price needs to reflect that. Buyers will factor in the cost and hassle of clearing everything out, so you have to set your expectations on price accordingly. If none of those options fit, you still have solid fallbacks. Facebook Marketplace and Craigslist move furniture fast locally. An estate sale company can handle everything in a single weekend with very little effort on your part. For nicer pieces, consignment shops or apps like Chairish are worth a look. The one thing I'd avoid is letting the furniture situation slow down your listing. Get the home on the market and deal with the furniture in parallel. Buyers generally respond best to clean, uncluttered spaces, so if pieces aren't moving, it may be worth clearing them out before showings ramp up.
Great question, Angie! This is one I hear a lot from sellers in the Orlando area. My general advice: skip the full kitchen renovation, but do invest in targeted, high-impact updates. A full kitchen remodel rarely returns 100% of its cost at resale aEUR" and in a market like Orlando where buyers have plenty of options, they'll factor the cost of their own future upgrades into their offer regardless. What you don't want to do is overspend on finishes that don't match the price point of your neighborhood. That said, a tired kitchen can absolutely hurt your first impression. Here's what I'd focus on instead: - Fresh paint on cabinets (white or a soft neutral goes a long way) - New hardware aEUR" pulls and knobs are inexpensive and make a big visual difference - Updated lighting fixtures - A clean, modern faucet - Decluttering and deep cleaning These cosmetic updates can run $500"$2,000 and genuinely move the needle on buyer perception without the risk of a full remodel. If appliances are more than 10"15 years old and visibly worn, replacing them with a matched stainless set can also help. The bottom line: present your kitchen as clean, functional, and updated aEUR" not brand new. Price the home accordingly and let buyers put their own stamp on it. Happy to walk through your specific home and give you a more tailored recommendation if you'd like! aEUR" Mike Fielder, Realtor
Janet, great question aEUR" and especially relevant for Philadelphia, where winters can definitely impact curb appeal and buyer traffic. Here's my honest take: The pros of selling in winter: - Less competition. Fewer homes hit the market in winter, which means your listing stands out more. Serious buyers are still out there and actively looking. - Motivated buyers. Anyone searching in December or January usually has a real reason aEUR" job relocation, lease ending, life change. These aren't casual lookers. - Faster closings. Lenders, inspectors, and attorneys tend to be less backlogged, which can actually speed up the transaction. The cons: - Smaller buyer pool overall. Foot traffic slows down, especially during the holidays. - Curb appeal challenges. No flowers, bare trees, and grey skies don't photograph as well. This is manageable, but you'll need to be intentional about staging and photos. - Weather-related delays. Inspections, showings, and even closings can get pushed around by snow and cold. My advice for Philadelphia specifically: if you need to sell or simply don't want to wait until spring, go for it aEUR" just price it right and invest in professional photography that shows the home's warmth and interior appeal. Make sure the driveway and walkways are always clear for showings, and lean into cozy interior staging (warm lighting, a clean fireplace, etc.). Waiting until March/April gives you peak buyer demand, but you'd also be competing with a lot more listings. It really comes down to your timeline and priorities. Feel free to reach out if you'd like a more personalized assessment of your situation! aEUR" Mike Fielder, Realtor
Yvonne, I'd push back on "we won't get permits in time" before accepting it. In Maryland your journeyman can't pull the permit, but a licensed master HVACR contractor can, and a lot of installers work under a master's license for exactly this reason. Ask your installer whose license he normally works under. If there's a master behind him, that company pulls the Montgomery County mechanical permit and he does the install. It's also worth asking why the buyer wants it permitted. I've had plenty of buyers ask whether permits were pulled and nothing ever came of it. Still, I'd want this one done right. I'm not an attorney, but unpermitted work can come back on a seller later. If a future buyer or inspector starts digging and something went wrong with the install, a missing permit is the kind of thing that can turn into a financial headache down the road. If the permit truly can't happen before closing, you still have options before the deal is at risk. You can ask the buyer to amend the addendum and extend the deadline, or allow the install shortly after settlement with funds held in escrow at closing (check with the buyer's lender first, since not every loan allows it). You can offer a credit instead and let the buyer choose their own contractor. Or get the second installer's timeline, because the price difference may be cheaper than a delayed or dead deal. Whatever you choose, get it in writing before any contract deadline passes. Missed deadlines kill more deals than the HVAC ever will. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Stella, there's no set time a seller has to respond, and they're allowed not to respond at all. I get this question a lot, partly because I'm also licensed in Pennsylvania, where the standard offer has a blank for an expiration date. Fill it in and the offer simply expires if the seller hasn't accepted by then. In Maryland that deadline isn't automatic, so ask your agent whether your offer included one. Either way, you can withdraw your offer any time before the seller signs it. What the listing agent can't do is sit on it. Maryland requires agents to present written offers to their seller promptly, so have your agent confirm yours was presented and ask when the seller plans to decide. From there, it comes down to why the seller is taking so long. I like to assume sellers are timely, and most are, but I've seen some strange situations. Sometimes it's an estate with five executors, two in California and two in Australia, and none of them agree. Other times a seller drags it out for days, seemingly just to collect as many offers as possible. If you've got another house you like, it's often best to pull your offer, or at least tell them you're about to, so you don't lose out on other properties while you wait. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Bette, it depends on what you signed. Since the 2024 rule changes, agents need a written agreement before showing you a home, and many of those agreements are narrow, covering one property or a few days. Pull out your copy and check three things: when it ends, whether it covers just that house or every home you buy in an area, and how it can be terminated. There should always be some kind of termination provision in there, whether it's mutual, unilateral, or both, plus any protection period after it ends. If it's limited to that one property or it's already expired, you're free to work with anyone. If it's broader and you're not happy, ask the agent for a written release. Most will give one, and if they won't, their broker can. Don't just ignore it, though. I've seen a case go before our local board where a buyer had an agreement in place but bought through a different brokerage, one of those that lets you book showings with the click of a button. The original broker went after them on procuring cause and won. Get the release in writing first. You can still visit open houses on your own. Just tell the listing agent up front that you've signed with someone else, so you don't end up owing two agents. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Sarah, yes, this is common. You'll find clean out companies in Maryland that will wait to be paid at settlement, but not all of them do it, so ask up front. Sometimes the agent fronts the cost and gets reimbursed at closing, or the estate pays from its own account if there are funds. A few things I'd watch for. Get the agreement in writing, including what happens if the sale falls through, since some companies charge a fee or interest for waiting. Get two or three quotes, because pricing on a full house varies a lot. Before anything gets hauled away, have the family pull photos, papers, and anything sentimental, and think about an estate sale company first. On a full house, an estate sale can sometimes cover most of the clean out cost. Also ask whether the house needs to be empty at all. Some buyers, especially investors, will take it as is with the contents, which can save weeks. The tradeoff is usually price, so have your agent run both numbers. If the house is in probate, check with the estate attorney before signing anything so the personal representative has the authority to commit the estate to that payment. I'm not an attorney, but that's the step that trips people up. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Chuck, you can sell it without fixing it first. Plenty of houses with foundation problems sell every year. The real questions are who buys it and at what price. Start with a structural engineer. A report usually runs a few hundred dollars and tells you whether the crack is cosmetic or structural, and what the repair is likely to cost. That number becomes your negotiating tool. Without it, buyers assume the worst and price the house that way. Then you've got a few paths. Listing it as is on the open market usually brings the highest price, but many lenders won't finance a home with significant structural problems, so your buyers may be cash buyers or people using renovation loans. Selling to an investor is faster and simpler, but you'll usually take a bigger discount. Some sellers also offer a repair credit at closing and let the buyer handle the fix. Whatever you choose, disclose it. Pennsylvania's seller disclosure asks about structural problems, and hiding a known foundation issue is the quickest way to end up in a dispute after closing. I'm not an attorney, so if you're unsure what to disclose, talk to one. A local agent can show you what homes with similar condition issues have sold for in Erie, which will help you pick the path that nets you the most. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Kayla, I'd take the emotion out of this and run both scenarios on paper. The right answer depends on your numbers more than on which way the area is heading. For selling now, get a realistic value from a local agent based on recent sales, not last year's prices. Subtract repairs, selling costs, and moving costs to see what you'd actually walk away with. Then price out a 5 bedroom (or a 4 bedroom with a finished basement or other flexible space) in the areas you'd consider, and figure out the monthly payment at today's rates. That part matters a lot. If you have a low rate on your current loan, giving it up could cost you more each month than the $50k you're worried about. For riding it out, be honest about the work the house needs and whether waiting makes it cheaper or more expensive. Deferred repairs on an older Victorian rarely get cheaper. One middle path is to do only the repairs that buyers' inspectors or lenders will flag and skip the cosmetic projects. That keeps more cash for your next down payment. If the math says you can't get into the right home yet, staying put while you save isn't a failure. It's a plan. Just make sure it's a decision you made with real numbers. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Emily, the way to make a lower offer without insulting a longtime owner is to show your work and keep the tone respectful. Before you write the offer, get real numbers. If the listing agent allows it, bring a plumber or contractor through on a second showing and get rough estimates. Then have your agent pull recent sales of both updated and dated homes in the neighborhood. The gap between those two tells you what the market already discounts for condition. When you submit, have your agent include a short summary with the comps and repair estimates attached. Keep the language about the cost of the work, not about the seller's home. "The plumbing will need about this much to bring up to date" lands much better than a list of everything wrong with the house. Remember that "as is" usually means the seller won't make repairs, not that you can't inspect. Keep an inspection contingency so you can walk away if the plumbing turns out to be worse than it looks. Finally, think about what else matters to this seller. After forty years in a home, a flexible settlement date or extra time to move out can matter as much as price. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Pam, it isn't automatically a bad investment, but a house with a collapsed roof and broken windows after 25 years empty is a major rehab, and the risk is in what you can't see yet. Once a roof fails, water usually gets into the framing, floors, and walls. Brick holds up well, but the wood structure inside it may not. Before you commit, have a structural engineer and a roofer walk it, and plan on the electrical, plumbing, and HVAC all needing replacement after that long. Mold is likely, and older homes can have lead paint or asbestos that adds cost. Then do the math backward. Figure out what the home would be worth fully fixed based on recent nearby sales. Subtract a realistic repair budget plus a 10 to 20 percent cushion, and your holding costs like insurance, taxes, and loan payments while the work gets done. If what's left doesn't give you a solid margin at your purchase price, offer less or pass. Also check whether you can insure or finance it in this condition, because many lenders and insurers won't touch a house with an open roof. A local agent can pull comps, and a local contractor can tell you what this kind of work costs in your area. If the numbers work with a cushion, it can be a rewarding project. If they only pencil out in the best case, keep looking. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Graham, it can work, and more buyers are asking about it. Just go in clear-eyed about what you'd get and what you'd give up. An attorney is great for reviewing the contract, explaining terms, and handling the legal side of closing. What they usually don't do is the work leading up to the contract: setting up showings, pulling comparable sales so you know what the house is worth, writing a competitive offer, and negotiating repairs after the inspection. That last part is often where a buyer's agent pays for themselves. On the commission credit, there's no automatic buyer's agent share sitting there for you to claim. If a seller is willing to pay something toward a buyer's agent, you can ask for that amount as a lower price or a closing cost credit instead, but the seller can say no. Keep in mind the listing agent works for the seller, not you. If you're financing, your loan program also limits how much the seller can credit and what it can cover, so check with your lender before you write the offer. One middle ground worth asking about: some agents offer a flat or reduced fee for limited services. I'm not an attorney and I'm not in Georgia, so talk with a local agent and a local attorney about how closings typically run there. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Harley, there isn't a set number. Commissions aren't fixed by law or by any industry standard. They're negotiable between the seller and their listing agent, and separately between a buyer and their agent. So the real answer depends on what was agreed to in the listing agreement and the buyer's agreement. What I can give you is the math so you can check any figure you're quoted. On a $545,000 sale, every 1% is $5,450, so multiply 5,450 by whatever percentage is in your agreement. Some agents charge a flat fee instead, in which case it's simply that amount. It also helps to know where the money goes. Commission is paid to the brokerage, not straight to the agent, and what the agent keeps after the brokerage split, marketing, and other costs is usually a good bit less than the gross number. If the sale already closed, your settlement statement from the escrow or title company shows the exact commission paid and to whom. If you haven't listed yet, interview a couple of agents, ask what's included in their fee, and compare the services, not just the percentage. The cheapest option isn't always the one that nets you the most at closing. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Sue, selling land yourself is doable, and it's usually simpler than selling a house. There's no structure to inspect, no showings to schedule, and fewer disclosures about systems and repairs. The work is in the prep and the paperwork. Before you list, gather what a lot buyer will ask for: the survey, the parcel number, zoning, whether public water, sewer, gas, and electric are at the street or whether it needs a well and septic, and any perc test results. Land buyers, especially builders, want to know what it'll cost to build there, and having those answers ready speeds everything up. Pricing is the hardest part. Land comps can be thin, so look at sold lots nearby over the last year or two, not asking prices. A local agent or appraiser can help if sales are sparse. For marketing, list it on the major for sale by owner and land sites, put a sign out, and reach out to local builders directly. They're often the most likely buyers for a lot that already meets township requirements. When you find a buyer, have a real estate attorney or title company prepare the contract and handle closing. I'm not an attorney and I'm not familiar with Michigan's specific rules, so that step is worth paying for. If you'd rather not deal with any of it, a local agent who sells land can take it off your plate. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Jamie, yes, unmarried couples buy homes together all the time, and you can both be on the mortgage. The lender will look at both of your incomes, credit, and debts, so talk to a lender early and run the numbers both ways. The bigger decision is how you hold title. The two common options are joint tenants with right of survivorship, where if one of you passes the other owns the whole house, and tenants in common, where you each own a share that can be unequal if one of you puts in more money. Your settlement company or an attorney can explain which fits you. I've lived this one. My wife and I bought two houses together before we were married, and we signed and notarized a cohabitation agreement that covered the house, among other things. Her family helped with the down payment, so it put everyone's mind at ease, and it was never mentioned again. I'm not an attorney, so have one draft yours, but put in writing who put in what, how you'll split costs, and what happens if one of you wants out. One more lesson from my own story: if you get married, take another look at the deed. About 12 years later, while we were buying an investment property, our title rep noticed both houses still had the wrong vesting for a married couple. A few hundred dollars in recording fees fixed it, but it's easier to handle on your own schedule than in the middle of a deal. Plan for the what-ifs while you're both still getting along. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Shane, it's true that a busy road usually shrinks the buyer pool a bit, and that tends to show up in price or days on market. It doesn't make your home hard to sell, though. Plenty of buyers care more about the house, the price, and the location than the traffic out front, and some like the easy access. A few things help before you list. Soften the noise with landscaping, a privacy fence, or a hedge along the front. Inside, good weatherstripping and solid windows make a real difference. Make the backyard the star: if it's private and quiet, stage it and feature it in the photos. Schedule showings outside rush hour when you can. Most important, price it right from day one. Your agent should pull comps on similar streets, not the quiet cul-de-sac around the corner. Overpricing a busy-road home is the fastest way to let it sit. I don't know the Fargo market specifically, so a local agent can tell you how much buyers there actually discount for traffic. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Kendra, on an older duplex, I'd treat a sewer scope as money well spent. A standard home inspection usually stops at the drains inside the house, so the line running out to the street goes unchecked. In older homes that line is often clay or cast iron, and tree roots, cracks, sags, and separated joints are common. With a duplex, two units' worth of water runs through that one line, so problems show up faster. A scope typically costs a few hundred dollars. A line repair or replacement can run into the thousands, especially if it means digging up a yard or sidewalk. If the camera finds something during your inspection period, you can ask for a repair or a credit, renegotiate, or walk away, depending on your contract. Ask for the video, not just the written summary, so a plumber can quote from it. I'm not in Ohio, so a local agent or the city can tell you how responsibility for the line is split between the owner and the city there. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Rowan, I'm sorry you're dealing with this. Moving fast is possible, but a few things tend to cause delays, so get ahead of them. First, confirm who can sign. If your parents can't sign themselves, you'll likely need a valid power of attorney that covers real estate, and the title company will want to review it early. I'm not an attorney, so if there's any question about authority, or if Medicaid or other benefits are involved, talk to an elder law attorney before you sell. Second, call a title company now. Have them check for liens, unpaid taxes, or old mortgages so nothing surprises you at closing. Third, decide between speed and price. A cash buyer can close in a couple of weeks but usually pays less. Listing with an agent, priced right and presented clean, often nets more and can still move quickly. A good agent can show you both numbers side by side. Finally, skip the big repairs. Clear out personal items, clean, fix anything that would scare a lender, and let the price reflect the rest. A local agent can tell you how fast homes like your parents' are selling in Lubbock right now. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Marisol, when you can't be there in person, a good local agent usually earns their keep. Off-market sounds faster, but the buyers who shop that way are mostly investors looking for a discount, especially on a unit that needs updating. You'd likely trade a chunk of price for convenience. A local agent can be your eyes and hands: meeting contractors, coordinating cleaners and photographers, handling showings, and managing the inspection and appraisal without you flying in. They can also help you decide which updates are worth it. Often that's paint, fixtures, flooring, and a deep clean, not a full renovation. Sort out a couple of things early. If there's a tenant, check the lease and decide whether to sell occupied or vacant. Request the HOA resale documents and ask about upcoming assessments, since those can delay closing or spook buyers. Loop in your tax professional too, since selling a rental has tax consequences. One middle path: ask a listing agent to get you a cash offer or two alongside a list-price estimate, so you can compare real numbers. Interview two or three agents who know that local market well. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Juniper, a 4.5% rate is worth taking seriously, but it's only one piece of the math. A few questions usually settle it. Does the rent truly cover the full cost? Add up the mortgage, HOA dues, insurance, taxes, a maintenance reserve, a vacancy cushion, and property management if you won't do it yourself. Also confirm the association allows rentals and whether any special assessments are coming. Do you need the equity? If selling lets you put more down and borrow less at today's rate, that savings can outweigh the low rate you'd give up. Your lender can run both scenarios and confirm whether you'd qualify carrying two mortgages. Do you want to be a landlord? Repair calls and tenant turnover are real, and it's a different job than owning a home. Finally, talk with a tax professional before deciding. I'm not a tax advisor, but how long you've lived there and how long you rent it can affect what you owe when you eventually sell. Run the numbers both ways with a local agent and your lender, and the answer usually becomes clear. Mike Fielder, REALTORA(R) | The Key Home Team of Cummings & Co. Realtors
Contact Information
Location
Social Media


Available Listings View All
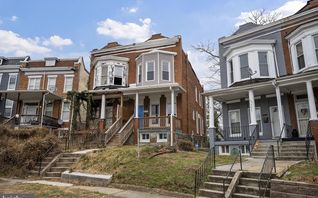
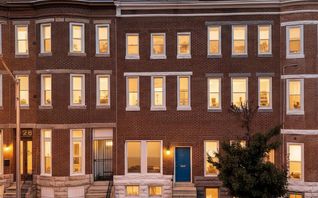 View All Listings
Trusted Professionals

Trusted Pro
Mike Fielder is a Trusted Pro with a network of verified professionals.
Real Estate Agent
CleaningOrganizing Services
 ZillowVERIFIED